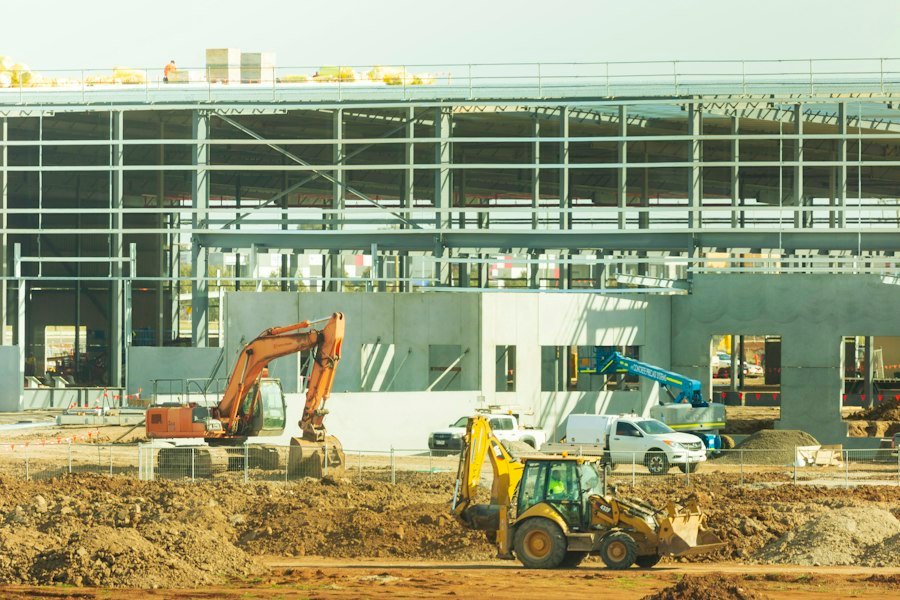
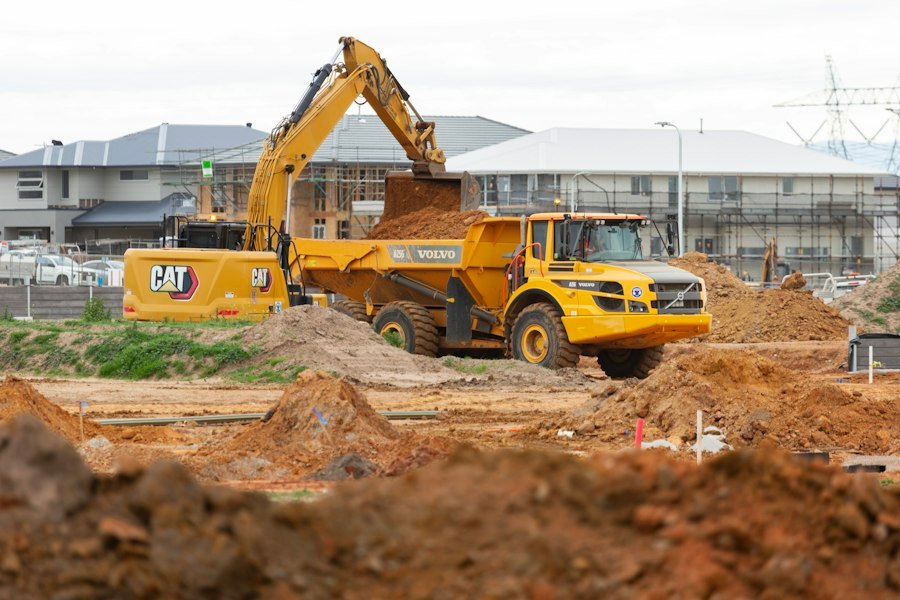
A teal excavator tipping soil into a dump truck on a Melbourne roads siteA yellow backhoe loader working a paddock site in Clyde North, VictoriaAn excavator and a backhoe loader on an industrial estate site in Truganina, VictoriaA yellow excavator loading an articulated dump truck on a housing estate site in Clyde North, Victoria

Machinery finance and loans for new and used machines

Tell us about the machine. A broker compares 60+ lenders and calls you with options.

Get a finance quote
Free, with no impact on your credit score
Confidential · Expert advice · No obligation
Pre-approval in as little as 24 hoursonce your application is complete
Rated 5.0 on from 102 reviews
No paperwork to startyour broker handles the entire deal, through to settlement
Trusted by 2m+ buyersevery year across our marketplaces

What our clients say on Google

  • Ali R.Aug 2026

    Chris handled everything, finding the finance, explaining everything clearly, keeping me updated, organising the paperwork and dealing directly with the dealership. All I really had to do was take a few phone calls and sign the documents online.

  • Micki B.May 2026

    We couldn’t recommend Ayman from EasyAsset more highly! As a start-up business, we had plenty of questions, and Ayman was always available to answer them, provide reassurance, and guide us through the process.

  • Stuart W.Sep 2026

    Chris was great to deal with, good communication, far less complicated than some of the other finance providers and much quicker.

  • Guru D.Jul 2026

    Chris provided outstanding service throughout the entire loan process. He was professional, knowledgeable, and always took the time to explain everything clearly.

EasyAsset finances the machines Australian businesses earn with, from mini excavators and skid steers to graders, telehandlers and forklifts. We also run IndustrySearch, where businesses get quotes on machinery from Australian suppliers. Your broker compares 60+ lenders, including specialists who understand hours, attachments and contract work, and handles the paperwork through to settlement.

What machinery can you finance?

New or used, from a dealer or a private seller. If you’re buying attachments with the machine, they can often go on the same loan.

Earthmoving and construction

  • Excavators
  • Mini excavators
  • Earthmoving equipment
  • Bulldozers
  • Backhoe loaders
  • Skid steers and bobcats
  • Wheel loaders
  • Graders
  • Construction equipment

Lifting and materials handling

  • Forklifts
  • Telehandlers
  • Cranes
  • Scissor lifts and boom lifts

Farm, mining and heavy machinery

Buying something other than machinery? See equipment finance. Still choosing the machine? Find it on our marketplaces, then come back with the quote.

Which type of finance suits your machine?

It comes down to how long you’ll keep the machine, your GST position and whether you want to own it. These are the main options.

Chattel mortgage

You own the machine from day one, and the lender holds a mortgage over it until the loan is paid off. It’s the structure we settle most often, and it usually suits a machine you plan to keep.

Finance lease

The lender owns the machine and you pay to use it. At the end of the term you can pay the residual, refinance it or hand it back.

Commercial hire purchase

You hire the machine over the term with fixed repayments, and ownership passes to you with the final payment.

Low doc loan

For self-employed operators whose financials aren’t up to date. Lenders usually skip BAS and bank statements and look at how long you’ve had your ABN, your credit file, any property you own and your deposit.

Operating lease or rental

You use the machine for a set period and give it back. It can suit a machine you only need for one contract, or one you replace often. With rent to buy, you can buy the machine at the end instead.

Sale and leaseback

Already own the machine? You sell it to a lender and lease it back, which frees up cash while you keep using it.

What lenders look at on a machine

A machine isn’t assessed like a car. These are the questions that decide which lenders will look at your deal, so it helps to have the answers ready.

01
Its age at the end of the term
Lenders care about how old the machine will be when the loan finishes, not only how old it is today. Some stop at 15 or 20 years, others go to 30, and we work with lenders for much older machines too. Age changes the risk, and with it the cost.
02
Hours on the meter
Hours do for a machine what kilometres do for a truck. High hours can change the rate and the term, and each lender sets its own limit. Have the current reading handy.
03
Make, model and resale
A common make with a strong resale market is easier to lend against than a rare or highly specialised machine, because the lender can value it and sell it if it has to.
04
Who’s selling it
A dealer sale is the simplest, and lenders treat an auction the same way. A private sale takes extra steps, and the lender may ask for an inspection or a valuation.
05
Attachments and fit-out
Buckets, augers, breakers and other attachments can often go on the same loan when they’re bought with the machine. Tell your broker early, so they’re on the invoice.
06
The work ahead of it
A signed contract or a steady run of work can help, especially for a newer business. If your income comes in seasons, some lenders can set repayments quarterly, half-yearly or yearly instead of monthly.

Three common machinery deals

No two deals are the same, but these are common starting points. Your broker gives you real numbers for your machine.

Civil contractor adding a second excavator
A used excavator from a dealer
TypeChattel mortgage
Approval pathFull doc
Owns the machine from day one, and a balloon can lower the repayments while the new contract ramps up.
Owner-operator buying a first machine
A skid steer with buckets and an auger
TypeLow doc loan
Approval pathABN, credit file and deposit
The attachments go on the same loan, so there’s one repayment and the machine is ready to earn from day one.
Warehouse replacing its forklifts
Several forklifts, replaced every few years
TypeFinance lease
Approval pathFull doc
Lets the business upgrade at the end of the term, without holding on to ageing machines.

Machinery finance calculator

Estimate my repayment

Adjust the sliders to estimate your repayments. Speak with our team for an exact quote based on your profile.

Loan amount $150,000
Loan term 5 years
Interest rate 7.5% p.a.
Repayment frequency
Estimated repayment
$3,006
per month
Loan amount$150,000
Total interest$30,342
Total repayable$180,342
Number of repayments60
Get an exact quote →
Indicative only. Actual repayments vary based on lender, credit profile, and fees.

New or used machinery?

Both can be financed, but lenders treat them differently. The right choice depends on your cash flow and how long you’ll keep the machine.

New machinery
More lenders, longer termsA new machine is lower risk for a lender, so more of them will look at the deal, and terms can run longer.
Check manufacturer finance on total costA manufacturer’s offer can look good on the headline rate. We compare it with the lenders on our panel on total cost, including every fee.
A larger GST claimA higher price means more GST. If you’re registered for GST, you may be able to claim it on your next BAS under a chattel mortgage.
Used machinery
Age at the end of the term sets the limitThat’s the figure most lenders start from. Hours affect the rate and the term, so older machines can suit a shorter loan.
Keep the service historyRecords and a recent inspection help a lender get comfortable with a used machine, especially in a private sale.
A balloon can lower repaymentsIt keeps monthly repayments down, but it means a lump sum at the end of the term, or a refinance.

Tax and GST, in plain terms

The structure changes what you may be able to claim. Talk to your accountant before you sign, and we’re happy to work with them.

GST

If you’re registered for GST and buy under a chattel mortgage, you may be able to claim the GST in the price on your next BAS.

Deductions

Under a chattel mortgage you may be able to claim interest and depreciation. Under a finance lease you may be able to claim the lease payments.

Instant asset write-off

Some smaller businesses may be able to claim an immediate deduction under the instant asset write-off. Limits and dates change, so check the current rules with your accountant.

Who qualifies for machinery finance?

Most lenders want an active ABN and a clear business use for the machine. Beyond that, it depends on the lender and your situation.

ABN and trading history
An active ABN is the starting point. A longer trading history opens up more lenders.
Self-employed without recent financials
Low doc lenders usually don’t need BAS or bank statements. They look at your ABN, credit file, property and deposit.
New businesses
Some lenders consider newer businesses with industry experience or a signed contract. Talk to us before assuming you won’t qualify.
Credit history
A clean history opens up more lenders. Some lenders will consider past credit problems, depending on your situation, so tell your broker early.
Security
The machine is usually the security, so many deals don’t need your house or other property.
Deposit
It depends on the lender, the machine and your business. Your broker tells you what each lender asks for.

From first call to settlement

1

Tell us about the machine

A few quick questions and no documents at this stage. A named broker then calls to talk through the machine, the price and when you need it.

2

The lender checks the value

Each lender checks the price against market guides and auction results, and lends against what the machine is worth. A deposit lowers the lender’s risk.

3

We compare 60+ lenders

Banks and specialist lenders, compared on total cost, including every fee. Pre-approval can take as little as 24 hours once your application is complete.

4

Settle and get to work

Your broker handles the paperwork, and the lender pays the seller at settlement.

Meet your brokers

Chris DebboLead Finance Broker, credit representative 535242Finalist, Broker of the Year, 2026 LMG Commercial & Asset Finance Awards
Ayman ZiadBusiness Development, credit representative 577946
Arrick AngSupport Broker

Machinery finance FAQ

How do I get a machinery loan?+
Send us your details and tell us about the machine. A broker calls to talk through the machine, the price and when you need it, then compares lenders on total cost, including every fee. You pick the offer and your broker handles the paperwork through to settlement.
What machinery can EasyAsset finance?+
Excavators, skid steers, loaders, graders, telehandlers, forklifts, cranes, tractors and other machines used in a business, both new and used. If you’re not sure about yours, ask your broker. They’ll tell you which lenders would look at it.
Can I get a machinery loan without security?+
On most machinery loans the machine itself is the security, so you often don’t need to offer your house or other property. Some lenders may ask for more on an older machine or for a newer business. A fully unsecured business loan is a different product and usually costs more.
Can I get low doc machinery finance?+
Yes, some lenders offer low doc loans for self-employed operators (some call them no doc). They usually skip BAS and bank statements and look at how long you’ve had your ABN, your credit file, any property you own and your deposit. The terms depend on the lender, the machine and your trading history.
Can I finance used machinery?+
Yes. Lenders look at how old the machine will be at the end of the term, its hours, and its make and model. Auction buys are treated like dealer sales. Private sales can be financed too, though they take extra steps and sometimes an inspection.
Do I need a deposit?+
It depends on the lender, the machine and your business. Your broker tells you what each lender asks for before you decide.
Can I finance attachments on the same loan?+
Often, yes, when they’re bought with the machine. Tell your broker early so the buckets, augers or other attachments are on the invoice.
What are machinery finance rates?+
Rates depend on the machine, its age, the term, the structure and your business, so there’s no single rate to quote here. The calculator gives you an estimate, and your broker gives you real offers to compare on total cost, including every fee.
Is EasyAsset a lender?+
No. EasyAsset is a business finance broker. We take your application to our lender panel and set the offers side by side for you.

Get your machinery finance quote today

Talking to us won’t affect your credit score.

Get my free quote
Get my free quote
Talking to us won’t affect your credit score.